Contact me by WhatsApp, email or video callContact me

Conversation creates clarity. Clarity creates confidence. Confidence produces results.

I help Ontario families and business owners turn their savings, investments and retirement into one deliberate strategy, built from better questions and explained in plain English.

Try our Goal Calculator: see what your goal takes each month.

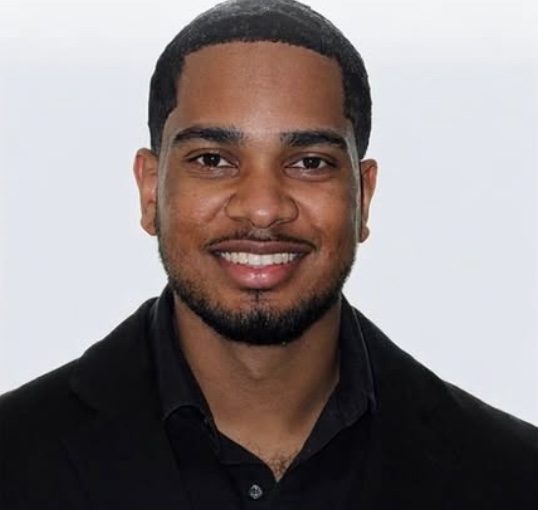
Franklyn Marshall, Founder & CEO, ClearestFinances Wealth Planning

Franklyn Marshall, Founder & CEO · Licensed Advisor, Ontario
Free · 30 minutes · No obligation, no sales pitch

Prefer to start on your own? Try the Whole Picture check-in →

What Happens

Three steps, at your pace.
You decide each one.

  1. 01

    Talk

    A private, complimentary 30-minute conversation about your situation and the questions on your mind. Nothing to prepare, and no pressure to decide anything.

  2. 02

    Organize

    I bring what you already have, your accounts, savings and benefits, together into one picture, so the gaps and overlaps are easy to see.

  3. 03

    Decide the next step

    That might be nothing, a paid working session, a referral to another professional, or looking at a product. It’s your call.

  • One personFrom your first call to your yearly review.
  • In writingYour 3 Moves arrive within 24 hours of the conversation.
  • Plain EnglishNo jargon, and no question is too basic.
  • PrivateYour details are never sold or shared.

“Financial planning is like navigation. If you know where you are and where you want to go, navigation isn’t such a great problem. It’s when you don’t know the two points that it’s difficult.”

— Venita VanCaspel
The Method

Most advice starts with an answer.
Mine starts with the right questions.

Before I suggest anything, I want to understand the decision behind the decision: what the money is really for, what would have to be true for you to feel secure, and what should happen to the plan if life changes course. The strategy is built from your answers, not from a product shelf.

  1. I

    Discovery

    A structured conversation that surfaces your goals, what you already have, and the trade-offs you haven’t named yet.

  2. II

    Strategy

    Which account gets the next dollar, in what order, and why. Tax, timing, family and protection weighed together, never one product at a time.

  3. III

    Stewardship

    Your strategy in writing, reviewed with you every year, and adjusted when your life does.

A few of the questions I’ll ask you

  • If your income stopped for six months, which account would you draw on first, and what would that choice cost you?
  • Is the money you’re saving for “later” sitting where “later” needs it to be?
  • If two of your goals compete for the same dollar, which one wins, and does your plan already know that?
Start with the questions
What I Can Help With

What we can work through,
and where it ends.

  • Your whole picture: accounts, benefits, debt and goals in one place, so you can see what you already have.
  • The order to save in: RRSP, TFSA, FHSA and RESP, and which one gets the next dollar for you.
  • Retirement income: your pension, CPP, OAS and savings in one picture, and the questions to ask about each.
  • Family and legacy: who receives what, and how, so the people you care about aren’t left guessing.
  • Keeping the plan standing: what happens to it if your income stops, and whether anything needs to change.

Tax, legal and mortgage advice belong with the appropriate professional. When that’s the case, I’ll say so and point you to one.

Complimentary and Paid

Start with the free conversation.
Paid sessions are optional.

The complimentary conversation is where most people begin. If a deeper working session would help, these are the options and their flat prices, listed before you book.

Most people start here

Complimentary Clarity Session

Free

30 minutes · phone or video

Best for: everyone, as the first step

  • Your One-Page Picture: income, accounts, debt, benefits and goals, together on one page during the call
  • Your 3 Moves: the three things that matter most for you right now, in order, texted to you within 24 hours
  • Your Next Step: if you need more, I’ll tell you which working session fits, and if you don’t, I’ll say so
Everything included
  • Your One-Page Picture
  • Your 3 Moves, texted within 24 hours
  • A quick unused-room scan: grants, employer matching and contribution room you may not be using
  • A Straight Answer: what’s working, what’s missing, and what needs attention first
  • Your Next Step
Book free

What Do You Actually Have? Account Review

$150

60 minutes · by phone

Best for: young professionals

A paid, 60-minute walkthrough of the accounts, policies and benefits you already have. Paid when you book; the cancellation policy below applies.

  • Your “What You Actually Have” Summary: everything on one page, yours to keep
  • FHSA vs. RRSP vs. TFSA: which one gets your next dollar at your tax bracket, and in what order
  • Your Top 3 Next Steps, emailed within 24 hours
Everything included
  • The Before-You-Call Checklist
  • The Plain-English Walkthrough
  • Your “What You Actually Have” Summary
  • An unused-room check (TFSA, RRSP, FHSA and employer matching)
  • FHSA vs. RRSP vs. TFSA
  • The Overlap & Gap Check
  • The Beneficiary Check
  • Your Top 3 Next Steps (emailed within 24 hours)
  • New: Your 12-month contribution order: which account gets each dollar, month by month
  • New: Your benefits, valued: what your work coverage is really worth, and what ends if you leave
  • The 30-Day Check-In (skip it anytime)

Questions most people never ask

  • If you changed jobs tomorrow, which of your benefits would disappear the same day?
  • Is your TFSA invested, or is it a savings account with a better name?
  • Who is named on every account you own, and is that still who you’d choose?
Book · $150

Mortgage Renewal Readiness

$395

60 minutes · phone or video

Best for: GTA homeowners renewing in the next 18 months

  • Your Renewal Game Plan: your monthly numbers before and after, and what changes
  • The questions to ask your lender or mortgage agent before you sign
  • A follow-up check-in after your renewal is done
Everything included
  • Your payment scenarios at a few realistic renewal rates and amortizations
  • What to protect and what to trim
  • Your emergency reserve through the renewal and after
  • Other debt: pay down before or after renewal
  • Mortgage protection: the lender’s insurance compared with coverage you own
  • The trap to avoid: solving the mortgage problem while creating a new one
  • New: Your renewal stress test: how many months you could carry the new payment on one income
  • New: Lump sum, RRSP or TFSA: what each choice for spare cash costs and gains you

I’m not a mortgage agent, so I don’t arrange mortgages or quote rates. Strategies discussed may involve life insurance products.

Questions most people never ask

  • If the payment rose $600 a month, what would you stop doing first?
  • Should spare cash go to the mortgage, an RRSP or a TFSA, and what does each choice cost you?
  • If one income stopped, how many months could you carry the new payment?
Book · $395

Family Plan Session for Couples

$450

75 minutes · by video · per couple

Best for: dual-income couples starting or growing a family

  • One household cash-flow plan: bills, savings and investing, in the right order
  • Parental leave and childcare: the budget while one income drops
  • A written roadmap you both keep
Everything included
  • One household cash-flow plan
  • Parental leave and childcare
  • Debt priorities
  • An emergency reserve that fits a GTA cost of living
  • RESP set up to capture every grant dollar
  • A safety net for both of you, not just the higher earner
  • Wills, guardianship and beneficiaries, with a referral to a lawyer if you need one
  • New: The one-income stress test: what holds, and what gives, if one of you stops working
  • New: A who-pays-what money system for two incomes, so nothing falls through
  • A written roadmap you both keep

Questions most people never ask

  • If one of you stopped working for a year, what changes first?
  • Does your will name a guardian, and does that person know?
  • When the RESP, the home and retirement all want the same dollar, which one wins?
Book · $450

Retirement Readiness Review

$495

75 minutes · phone or video

Best for: pre-retirees, 50 to 65

  • Your Retirement Income Map: where each dollar of retirement income comes from
  • A short list of decisions, in order, with dates
  • A follow-up check-in within 30 days
Everything included
  • Your retirement income picture: pension, CPP, OAS, RRSP, TFSA and savings, side by side
  • The gap: what you’ll have each month compared with what you want to spend
  • CPP and OAS timing
  • RRSP to RRIF: when to convert, and an order for drawing from each account
  • The surviving spouse
  • Estate basics
  • Costs and coverage you may no longer need
  • New: Your withdrawal order: which account to draw from first, to smooth tax and limit OAS recovery tax
  • New: Income for life or flexibility: the trade-off, laid out for your numbers
  • The questions to bring to your accountant, lawyer or current advisor

Questions most people never ask

  • In which year of retirement does your tax bill peak, and can it be moved?
  • If one of you passes first, what income does the survivor lose?
  • Which account should you spend from first, and which should you leave alone longest?
Book · $495

Owner’s Pay & Protection Session

$750

90 minutes · phone or video

Best for: established business owners and the self-employed

  • Your Owner’s Money Map: business cash flow, personal pay, reserves and savings on one page
  • A written 5-to-20-year action plan, in order
  • A follow-up check-in within 30 days
Everything included
  • Paying yourself from uneven business cash flow
  • Salary, dividends and retained earnings: the trade-offs
  • Wealth outside the business
  • Protection: disability, critical illness, life, key person and partner coverage
  • Your exit
  • Beneficiaries and estate basics, coordinated with your lawyer
  • Complex strategies for when your RRSP and TFSA are full
  • New: Personal or corporate: where your next dollar of savings should sit, and why
  • New: Your exit timeline: what has to be true, and by when, for the business to fund your retirement
  • The questions to bring to your accountant and lawyer

Strategies discussed may involve life insurance products.

Questions most people never ask

  • If you couldn’t work for six months, does the business keep paying you?
  • How much of your retirement depends on selling a business no one has valued?
  • If a partner died tomorrow, who would own their share, and with what money?
Book · $750
Ongoing relationship

Annual Strategy & Stewardship

$1,200 a year · or $100 a month

Best for: anyone who wants their plan looked after, not just made

  • Your written strategy, kept current: every account, benefit and protection in a deliberate order
  • A 90-minute annual strategy review and a 30-minute mid-year check-in
  • Direct access by WhatsApp or email between meetings, for the decisions that can’t wait a year
  • Coordination with your accountant and lawyer, so the plan, the tax return and the will agree
  • Referrals when you need them: if your situation calls for portfolio management, I’ll introduce you to a CFP® professional I trust
Book · $1,200 a year

Questions most people never ask

  • What changed this year that your plan doesn’t know about yet?
  • Are you still saving in the right order for the life you have now?
  • Which decision are you putting off, and what is waiting costing you?

All prices are flat, in CAD, taxes included. Cancel or reschedule any time before your session for a full refund. Full policy

Who I am, what I don’t do, and how I’m paid →

Plan a Goal

A home, a car, a wedding.
What does it take each month?

Pick what you’re saving for and when you want it. You’ll see the monthly amount, and the kind of account worth asking about.

All 12 calculators →

Goal Calculator

Hypothetical

What are you saving for?

Save about $1,269

a month for 5 years to reach $80,000.

a month every two weeks a week

Your deposits , growth .

Hypothetical illustration, not a guarantee or a projection of any investment. Assumes the same deposit at the end of every month and a steady rate. Fees and tax are not included.

Want a plan to get there? Arrange a complimentary conversation
Founder & CEO

I’m Franklyn.

I watched people close to me do everything right — work hard, show up, build something real — and when something went wrong, the system didn’t protect them.

Why I do this work

I founded ClearestFinances Wealth Planning and lead every client relationship myself. I’m a Licensed Advisor working with business owners, couples and growing families, young professionals and pre-retirees across the GTA and the rest of Ontario.

I don’t start with products. I start with the structure behind your goals: which accounts to use and in what order, what keeps the plan standing if life goes sideways, and who it all goes to. We set it up properly once, then review it together every year.

My work is built on questioning. The first conversation is a careful discovery, so the strategy that follows fits your life rather than a template.

Licensed and regulated by FSRA. My recommendations must be suitable for your needs and goals, and I’m required to treat you fairly.

About Franklyn. Franklyn Marshall is the Founder & CEO of ClearestFinances Wealth Planning and a Licensed Advisor in Ontario (FSRA #22207349), contracted with iA Financial Group through Benefits By You Agency. Check the licence on FSRA’s public register (opens in a new tab)

Read my story →

Start on Your Own

Not ready to talk yet?

These work on your own, with no sign-up to see the result. Your numbers never leave your browser.

All calculators →

Or read a short guide (free PDF)

RRSP Refund Estimator

2026 · Ontario
Estimated refund $4,341

About 43¢ back on every dollar you put in.

An estimate using 2026 federal and Ontario tax rates and the basic personal amounts only. It assumes you have enough personal RRSP deduction room; your limit is on your CRA Notice of Assessment and may be lower than the $33,810 2026 dollar limit. Your real refund depends on your other income, credits and deductions, and on how much tax was already taken off your pay. Not a guarantee.

Want to check this against your real numbers? Arrange a complimentary conversation
Examples

Examples of what a conversation looks at.

Illustrations with their assumptions stated. They are not recommendations or forecasts, and what applies to you depends on your own situation.

An RRSP example ~$18,100 refund on $33,810, top bracket

Assumes income above $258,482 taxed at Ontario’s 2026 top combined rate of 53.53%, and enough personal RRSP room. $33,810 is the 2026 dollar limit; your own deduction limit is on your Notice of Assessment.

A probate example $14,250 tax on a $1M Ontario estate

Ontario’s estate administration tax is $15 per $1,000 above $50,000. Whether an asset passes outside the estate depends on its ownership, beneficiary designation and contract type; a lawyer can confirm.

A TFSA example $109,000 most room anyone has in 2026

Only for someone eligible every year since 2009 who has never contributed. $7,000 is new in 2026. Your own room is in CRA My Account.

A business example Order matters taking money out of a corporation

Money in a corporation is generally taxed again when it comes out to you. The trade-offs are worth laying out with your accountant, who confirms the numbers.

Situations people have brought me

Business owners

Commercial cleaning

More sitting inside the corporation than anyone had ever properly explained to him — and no plan for moving any of it out.

Clinic

A practice owner whose entire income depended on her being well enough to work, and whose partners had never put an agreement in writing between them.

Construction company

An owner with a crew on payroll who had never worked out what happens to the contracts, or to the people depending on them, if he is the one who gets hurt.

Restaurant

An owner who had personally signed for the lease years ago, and had never thought through what that signature means for the family if he isn’t there.

See more situations
Nursing

Two nurses on opposite shift patterns, working toward a down payment without dismantling what they’d already built.

Family history

Someone with a condition that runs in their family, who wanted a plan in place while the decision was still entirely theirs to make.

Newly married

A couple three months in, merging two sets of accounts and two fairly different instincts about money.

Parents

Parents who opened an RESP years ago and had never found out whether they were actually collecting the full government grant.

Construction

A framer who had never once thought about what happens to the mortgage if his back goes.

New graduate

Someone a year into their first real job, weighing student loan payments against starting to save — and being told to do both by people who had never seen the numbers.

Described in general terms. No client is identified, and none of these describes a specific result.

Before You Book

Questions people ask

Am I going to be sold something?

No. The conversation starts with your situation and your questions. Plenty of people leave with a clearer picture and nothing else, and that's a good outcome. If anything is ever recommended, it's because it fits your situation, and the decision is always yours.

What should I bring?

Nothing is required. If you have a pension or investment statement, a benefits booklet or a corporate statement handy, it helps, but most people just show up and talk.

What can you help with?

Getting your accounts and benefits into one picture, the order to save in, your retirement income, and who receives what. Tax, legal and mortgage advice belong with the appropriate professional, and I'll tell you when that's the case.

I already have an advisor or accountant. Why talk to me?

Keep them. Your accountant handles tax filing and the books. I look at what sits around it: the order you save in, how it all fits together, and what passes to your family. Plenty of people use the conversation as a second look.

Can I book a paid session directly?

Yes. The paid sessions and their flat prices are listed above. If you'd rather see how I work first, start with the complimentary conversation.

Why is the first conversation free?

Because the only way to know whether I can help is to look. Some people go on to work with me; many just leave with a clearer picture. Both are fine.

When You’re Ready

Arrange a complimentary conversation

Thirty unhurried minutes, by phone or video. No obligation and no sales pitch.

Or pick a time right here:

Or Write To Me

Not ready to pick a time?
Send a question instead.

One honest question is a fine place to start. I read every one of these myself and reply personally.

Prefer your own email? franklyn.marshall@agc.ia.ca